If you searched this and landed on a national article, you probably got the wrong answer.
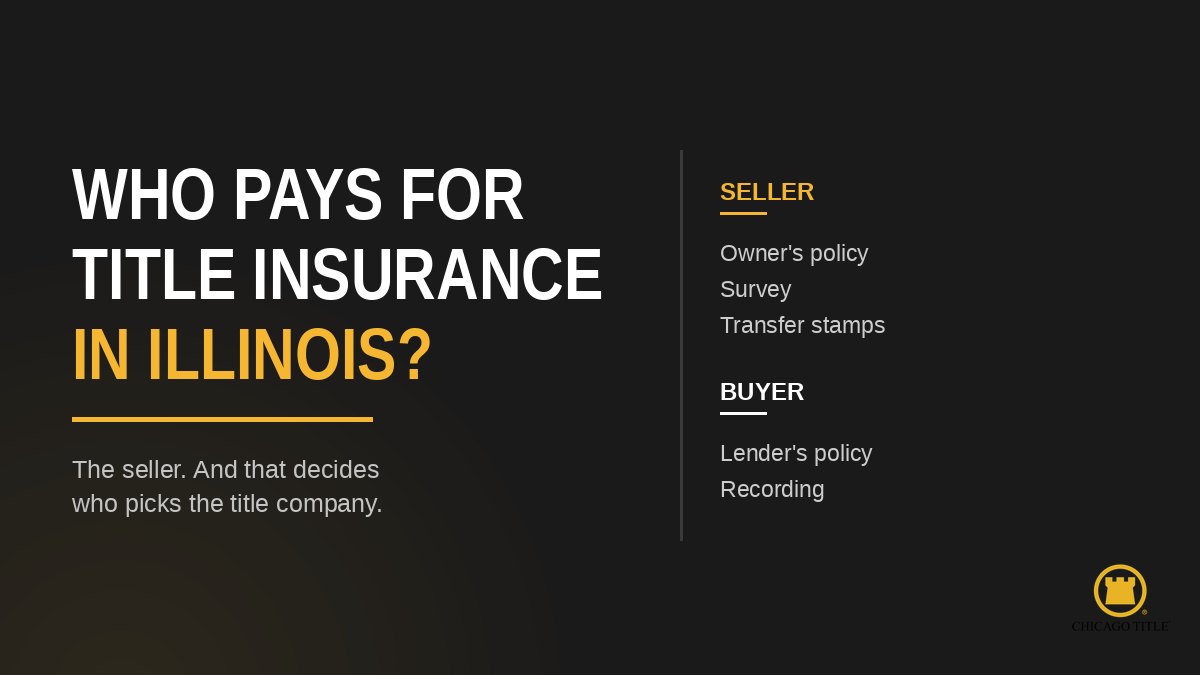
In Illinois, the seller pays for the owner’s title insurance policy. The policy protects the buyer. That combination surprises people. The more useful point is that there is no national answer at all. Texas and Washington also put it on the seller. In Florida and California it changes by county, so two closings in the same state land on opposite sides of it. Illinois is settled on the seller side, and that is exactly why a national article is the wrong place to look this up.
It also matters more than it sounds like it should. In Illinois, whoever pays for the title insurance gets to pick the title company. So “who pays” is not trivia. It decides who makes the call.
Here is the full picture of who pays what at an Illinois closing, where each allocation actually comes from, and the two places people get it wrong.
Who pays for title insurance in Illinois?
The seller, for the owner’s policy.
Paragraph 20 of the Multi-Board Residential Real Estate Contract 8.0, the form most residential resales in Chicagoland run on, puts it plainly. At Seller’s expense, the seller delivers a title commitment for an ALTA title insurance policy in the amount of the purchase price, with extended coverage, issued by a title company licensed in Illinois, and causes a policy to issue with an effective date as of closing.
Three things in that sentence are worth slowing down on.
At Seller’s expense. Not negotiable by default. It is the seller’s cost unless the parties agree otherwise.
In the amount of the Purchase Price. The coverage tracks what the buyer paid, not the loan amount and not the assessed value.
With extended coverage. The standard exceptions get deleted. There is one exception to the exception: extended coverage is not required when the property is vacant land.
The buyer pays for the lender’s policy. More on that below.
Why does the seller pay for a policy that protects the buyer?
This is the part that feels backwards, and the answer is in how Paragraph 20 describes the commitment: it is evidence of title in Seller.
The seller’s central promise in the contract is to convey good and merchantable title. The title policy is how the seller proves it. The buyer is the one insured, but the reason the document exists is to back up what the seller said.
Read that way it stops being strange. The seller is not buying the buyer a gift. The seller is paying to demonstrate that what they are selling is actually theirs to sell.
Paragraph 20 keeps going in the same direction. If the commitment turns up unpermitted exceptions, or the survey shows an encroachment the buyer will not accept, the burden is on the seller to get those removed or insured over before closing. The seller also furnishes an Affidavit of Title at closing.
Who pays for the lender’s policy?
The buyer.
A lender’s policy insures the lender, not the buyer, up to the loan amount, and it goes away when the loan is paid off. Paragraph 8(a) of the Multi-Board contract puts loan costs on the buyer: origination fees, discount points, and closing costs charged by the lender. The contract never names the lender’s policy directly, but it is a loan cost. It appears on the buyer’s loan estimate and lands on the buyer’s side of the settlement statement.
When both policies are issued at the same time on the same transaction, title companies commonly issue the lender’s policy at a reduced simultaneous rate rather than charging full price twice. It is still a real cost on the buyer’s side, just a smaller one than the owner’s policy.
Does paying for the title insurance mean you pick the title company?
In Illinois, yes, and it is written into the statute.
215 ILCS 155/18.1 declares it Illinois public policy that parties to a contract for the sale of residential real property who are obligated to provide and pay for title insurance have the right to choose the title insurance company and the title insurance agent. The same section prohibits a lender or a producer of title business from requiring that party to use a different one as a condition of making a loan or providing services.
Follow the chain and the practical result is clear. Under Paragraph 20 the seller is obligated to furnish and pay for the owner’s policy. Under 18.1 the seller therefore chooses the title company.
For a listing agent, that is worth knowing before the contract is signed rather than after.
Can a seller make the buyer use a particular title company?
No, and this is the place people get in trouble.
RESPA Section 9, at 12 U.S.C. 2608, says no seller of property that will be purchased with the assistance of a federally related mortgage loan shall require, directly or indirectly, as a condition to selling the property, that title insurance covering the property be purchased by the buyer from any particular title company.
The penalty is not a slap. A seller who violates it is liable to the buyer for three times all charges made for that title insurance.
So how do these two rules coexist?
They cover different purchases. The seller choosing the company for the policy the seller is buying and paying for is fine, and Illinois law specifically protects it. The seller conditioning the sale on the buyer buying the buyer’s title insurance from a named company is what Section 9 forbids.
The line is who is writing the check for that particular policy. If a seller starts dictating where the buyer’s coverage comes from, the seller has crossed it.
Who pays the transfer taxes?
State and county fall on the seller. Municipal depends entirely on the local ordinance.
The statutes write these rates per $500, because that is how the stamps are actually calculated. Per $1,000 is easier to hold in your head.
- State: 50 cents for each $500 of value, which is $1.00 per $1,000 (35 ILCS 200/31-10)
- County: 25 cents for each $500 of value, which is $0.50 per $1,000 (55 ILCS 5/5-1031)
Together that is $1.50 per $1,000 on the seller. On a $400,000 sale, $400 to the state and $200 to the county, so $600 before any municipal tax enters the picture.
Both taxes are levied on the privilege of transferring title, and courts reading that language have noted the only party with that privilege is the seller. Paragraph 18 of the Multi-Board contract matches: the seller delivers the deed with real estate transfer stamps paid, unless a local ordinance designates otherwise.
That last clause is doing real work. Paragraph 19(a) makes it explicit that the cost of transfer taxes imposed by municipal ordinance is paid by whichever party the ordinance names.
Municipal is where the assumption breaks. Home rule municipalities in Illinois set their own transfer tax and name their own payer, and all three patterns are out there: seller pays, buyer pays, and split down the middle. Seller is the most common by a wide margin, but buyer paying towns are not unusual, and several of them are substantial Chicagoland suburbs.
Chicago is the best known example rather than the only one. The city tax is split, with the larger share on the buyer and the CTA portion on the seller. I wrote up the Chicago transfer tax in detail here, including the certificates that stop closings when nobody ordered them in time.
The practical rule is short. Never assume the municipal piece follows the state and county. Check the ordinance for that specific town, every time, because the answer genuinely changes across a county line and sometimes across a village line.
Who pays for the survey?
The seller, and it is a requirement rather than a courtesy.
Paragraph 21 obligates the seller, at the seller’s expense, to furnish a plat of survey no less than one business day before closing. It has to conform to the current Illinois Minimum Standards for a boundary survey, be dated not more than six months prior to closing, and be prepared by a land surveyor licensed in Illinois. The surveyor has to set monuments or witness corners at all accessible corners, and those corners have to be visibly staked or flagged.
The contract also closes a loophole by name: a mortgage inspection is not a boundary survey and is not acceptable.
The carve out is condominiums. No survey required.
Who pays the title company’s closing fee?
This one is decided by a checkbox on page two, and it is the allocation people most often get wrong.
Paragraph 8 asks the parties to initial exactly one of three financing subparagraphs, and each one handles the escrow closing fee differently.
8(a), financing contingency. The buyer pays the title company escrow closing fees, alongside origination and other lender charges.
8(b), cash transaction with no financing. The parties share the title company escrow closing fee equally.
8(c), cash transaction, financing allowed. The buyer pays the fee if the buyer obtains a mortgage. If the buyer elects to close without a mortgage loan, the parties share it equally.
Same form, same fee, three different answers depending on which box got initialed weeks earlier. If you are reconciling a settlement statement and the closing fee is not where you expected it, check page two before you call anyone.
Is title insurance required in Illinois?
No Illinois statute requires a buyer to carry an owner’s policy. In practice it is close to universal anyway, for two reasons that have nothing to do with a mandate.
If there is a mortgage, the lender requires its own policy as a condition of funding. That is not a choice the buyer gets to make.
And if the deal is on the Multi-Board contract, Paragraph 20 obligates the seller to provide the owner’s policy whether the buyer asked for it or not. A buyer would have to affirmatively negotiate the coverage away, which essentially nobody does, because the policy costs them nothing.
Who pays more, the buyer or the seller?
Closer than most people assume, and the answer turns on whether the buyer is financing.
The pattern underneath is easier to remember than the list. Costs attached to the property land on the seller. Costs attached to the loan land on the buyer. A cash buyer carries very little. A buyer with a mortgage picks up origination, points, the appraisal, the lender’s policy and usually the escrow closing fee, which can add up to more than the seller is carrying.
| Item | Who pays | Where it comes from |
|---|---|---|
| Owner’s title policy and commitment | Seller | Paragraph 20 |
| Plat of survey (not condos) | Seller | Paragraph 21 |
| State and county transfer stamps | Seller | Paragraph 18, 35 ILCS 200/31-10 |
| Municipal transfer tax | Whoever the ordinance names | Paragraph 19(a) |
| Curing title exceptions | Seller | Paragraph 20 |
| Real estate tax proration | Seller credits buyer | Paragraph 12 |
| Lender’s title policy | Buyer | A loan cost, not named in the contract |
| Origination, points, lender charges | Buyer | Paragraph 8(a) |
| Title company escrow closing fee | Depends on the financing box | Paragraph 8(a), 8(b), 8(c) |
| Recording the deed and mortgage | Buyer, by practice | Contract is silent |
| Each side’s attorney | Each party | Contract is silent |
Two rows in there are worth a second look.
Real estate tax proration. Illinois taxes are paid in arrears, so the seller owes for time they already occupied the property but have not been billed for yet. Paragraph 12 prorates to and including the date of closing based on a percentage of the most recent ascertainable full year tax bill, and that percentage is a blank the parties fill in. It is a negotiated number, not a fixed one.
Recording. The contract does not allocate it, so practice fills the gap: the buyer’s side records the deed and the mortgage, and the seller pays to record releases of existing mortgages and liens, because clearing those is part of delivering good title. I covered Cook County recording requirements and costs here.
One caveat worth taking seriously
Everything above is the default under one specific form.
The Multi-Board 8.0 is the most common residential contract in Chicagoland, but it is not the only one, and every allocation in it is a starting point rather than a rule. Attorney review exists partly so these terms can move. New construction contracts, deals written on some other form, and anything commercial can allocate costs in a completely different pattern.
Custom tells you what to expect. The contract in front of you tells you what is actually true. When those two disagree, the contract wins.
If you are looking at a deal and the numbers are not landing where this article says they should, that is usually a sign somebody negotiated it, not a sign somebody made a mistake. Worth a read of the rider before anyone gets on the phone.
For what the rest of closing day looks like, I wrote a walkthrough of an Illinois closing from start to finish.
If you are the seller, it is your call
That is the part worth carrying out of all this. In Illinois the seller usually pays for the owner’s policy, and under 155/18.1 that makes the title company the seller’s choice. It is a decision a lot of sellers never realize they are making, because it quietly defaults to whoever the other side suggests first.
I am a Vice President at Chicago Title and I work with attorneys and realtors across Chicagoland. If you want to walk through a specific file, reach out.
Sources
- Multi-Board Residential Real Estate Contract 8.0, Paragraphs 8, 12, 18, 19, 20 and 21
- 215 ILCS 155/18.1, Choice of Title Insurance Company, Illinois Title Insurance Act
- 12 U.S.C. 2608, RESPA Section 9, Title companies, liability of seller
- 35 ILCS 200/31-10, Illinois Real Estate Transfer Tax Law
- 55 ILCS 5/5-1031, county real estate transfer tax
- Attorneys’ Title Guaranty Fund, Transfer Taxes in Illinois
- Illinois REALTORS, Title Insurance Choice in Illinois